A business owner checks the sales report on Friday and sees three large proposals. The total looks reassuring. Then one customer delays a decision, another asks for work outside the quote, and the third proposal has no next meeting. The forecast had treated possibilities as if they were commitments.
A useful sales pipeline forecast helps you plan around uncertainty. It shows what may happen, what evidence supports that view, and what still needs attention. It should not turn every conversation into promised revenue. A sales pipeline forecast is a planning view, not a promise that every open deal will close.
Start with a clear definition of each stage
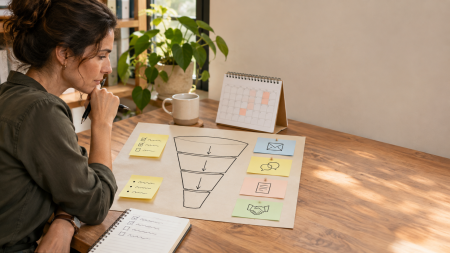
A pipeline is the set of potential sales moving through your business’s buying process. Your stages should describe something the buyer has actually done, not how optimistic the seller feels. For example, “first conversation held” is easier to verify than “high interest.” A proposal stage might require that the buyer has confirmed the problem, decision process, expected timing, and the people who need to approve the purchase.
Choose a small number of stages that fit how your customers buy. A consulting firm, a distributor, and a subscription service may need different stages. Keep the definitions short enough that two people would classify the same opportunity in the same way. Review them with the people who speak to prospects. The sales pipeline forecast becomes easier to compare when the team keeps those definitions stable.
Separate signed work from open opportunities
Keep signed orders or contracts in a committed-work view, subject to your normal conditions for recognizing the work. Keep proposals, verbal interest, and early conversations in the pipeline. This distinction matters when you decide whether to hire, buy materials, reserve delivery capacity, or spend money on a new initiative.
For each open opportunity, record the customer, likely value, current stage, evidence for that stage, expected decision date, named owner, and next action. Include delivery effort or capacity where it could affect what the business can accept. A large opportunity may need more review if it depends on a scarce skill, an unusual supplier, or a demanding start date.
Use evidence before assigning a probability
Some forecasting methods multiply the value of an opportunity by a stage probability. That can help summarize a large pipeline, but a percentage is useful only if it reflects your own past results and a stable stage definition. A generic probability copied from another business can give a precise-looking total without giving you better information. Keep the sales pipeline forecast tied to evidence the team can explain.
Start with your closed and lost opportunities. Group them by the stages and conditions that matter to your business. Ask how often opportunities at each stage reached an agreement, how long decisions took, and whether the pattern changed when the source, product, customer type, or sales process changed. If you have too little history for a dependable estimate, show a range or keep the opportunity unweighted. Say that the estimate is uncertain.
The UK government’s investment guidance describes pipeline stages, estimated values, and probabilities as part of revenue planning for startups and scaleups preparing for investment. That is useful context for that audience, not a universal probability table for every company. The U.S. Small Business Administration also connects a company’s marketing and sales strategy with its financial projections. In either case, the owner still needs assumptions that fit the business and market.
Build a forecast that helps make a decision
Separate the view you use for near-term delivery planning from a longer-term planning estimate. A signed project scheduled to start next month has different evidence from a proposal that may close next quarter. Show the time period, what counts as committed, and which assumptions drive the open-opportunity estimate.
Imagine a small service firm with two signed projects and three proposals. In this illustrative example, the team records the signed work in its delivery plan. The proposals remain open. Each has a buyer-confirmed next step and an expected decision date. The owner compares the possible start dates with staff capacity before agreeing to any new commitment. These invented details are a teaching example, not a client result or benchmark.
Do not use a weighted pipeline total as a cash-flow forecast. Even a signed project may have deposits, milestones, acceptance steps, and payment terms. A forecast of sales activity answers what work might be won. A cash forecast asks when money is expected to arrive and leave. Keep the assumptions distinct, then reconcile them in the business’s financial planning.
Review changes, not just totals
At a regular review, compare the previous forecast with actual outcomes. Which opportunities moved forward, stalled, changed value, or disappeared? Did the expected decision dates prove realistic? Did delivery capacity prevent the business from accepting work? A short note on why a major assumption changed will make the next forecast easier to judge. This turns the sales pipeline forecast into a learning record, not only a month-end total.
Assign one owner to update each opportunity and one person to challenge the overall assumptions. Remove duplicates and close opportunities that no longer have a credible next step. Keep a dated copy of the previous view so that the team can see whether the forecast changed because of new evidence or a changed definition.
Make the forecast useful to the whole business
A sales forecast influences more than sales. Operations may need to plan capacity. Finance may need to model timing and risk. Managers may need to decide whether to recruit, use a partner, or delay optional spending. Bring those people into the discussion before an uncertain opportunity becomes an operational promise.
Start with a simple shared record if the team is small. A spreadsheet can work when one person owns updates, the stages are clear, and changes are visible. More software will not fix unclear definitions or missing follow-up. If the process grows, choose a system only after deciding what information each role needs and how it will stay accurate.
DBG360 can help a business map its sales stages, test the assumptions against operating capacity, and connect pipeline planning to financial and delivery decisions. If your forecast is driving commitments that the team cannot yet support, contact DBG360 to discuss a practical review.
Sources and scope
- UK government guidance on financial models and revenue pipelines for startups and scaleups. Used for the bounded description of staged opportunities, estimates, and conversion evidence.
- U.S. Small Business Administration business planning guidance. Used for its statement that marketing and sales strategy informs financial projections. U.S. government guidance; not a rule for Georgia or other jurisdictions.
This article offers general business-planning guidance. It does not give legal, accounting, tax, or investment advice. Revenue recognition, contract terms, and tax treatment depend on applicable standards and local requirements.